A low credit score can make buying a vehicle feel out of reach, but it rarely closes the door completely. If you live in Kitchener, Waterloo or Cambridge and need a reliable vehicle, there are lenders and dealerships that work with credit challenges every day. What changes is how the approval is decided, how much the loan costs, and what you can do to improve your odds.
This guide explains how bad credit car loans in Kitchener are approved, what lenders look at, which documents to prepare, what interest rates and loan terms to expect, and how a truck loan differs from a standard car loan. Whether you are rebuilding after missed payments, new to Canada, or a student with no credit history, you will know what to expect before you apply. If you would rather talk to someone first, you can explore our financing options at any time.
What Counts as "Bad Credit" for a Car Loan in Ontario?
In Canada, credit scores from Equifax and TransUnion range from 300 to 900. Lenders set their own cut-offs, but as a rough guide, scores below about 600 to 660 are often treated as subprime or "bad credit." A lower score signals higher risk to the lender, which usually means a higher interest rate, a larger down payment request, or both.
Common reasons for a lower score include:
- Missed or late payments on credit cards, loans or bills
- Accounts in collections
- A consumer proposal or past bankruptcy
- High credit card balances compared with your limits
- A previous vehicle repossession
Bad Credit vs. No Credit
Not having a credit history is different from having a damaged one, but lenders often treat both cautiously. Newcomers to Canada and students are common examples. With no history, a lender has little to judge, so they focus more on your income, employment and down payment. Our guide to car buying for students in Canada covers this situation in more detail.
How Bad Credit Car Loan Approval Works, Step by Step
The process is more straightforward than most people expect:
- Set a realistic budget. Decide what monthly payment fits comfortably after rent, insurance, fuel and savings. Our guide on how much car you can really afford shows how to work this out.
- Check your credit reports. You can request your Equifax and TransUnion reports for free and look for errors, such as accounts that are not yours or debts you already paid.
- Gather your documents. Having everything ready speeds up the decision (see the checklist below).
- Submit a credit application. The dealership or lender reviews your income, credit history and debts. At a dealership, the finance team often sends your application to several lenders at once, including those that specialize in subprime credit.
- Review the offer carefully. Look at the interest rate (APR), the term, the monthly payment and the total cost of borrowing, not just the payment.
- Choose a vehicle within your approved amount. Once you pick a vehicle, the lender confirms it meets their requirements (age, mileage, price), you sign the paperwork, arrange insurance and take delivery.
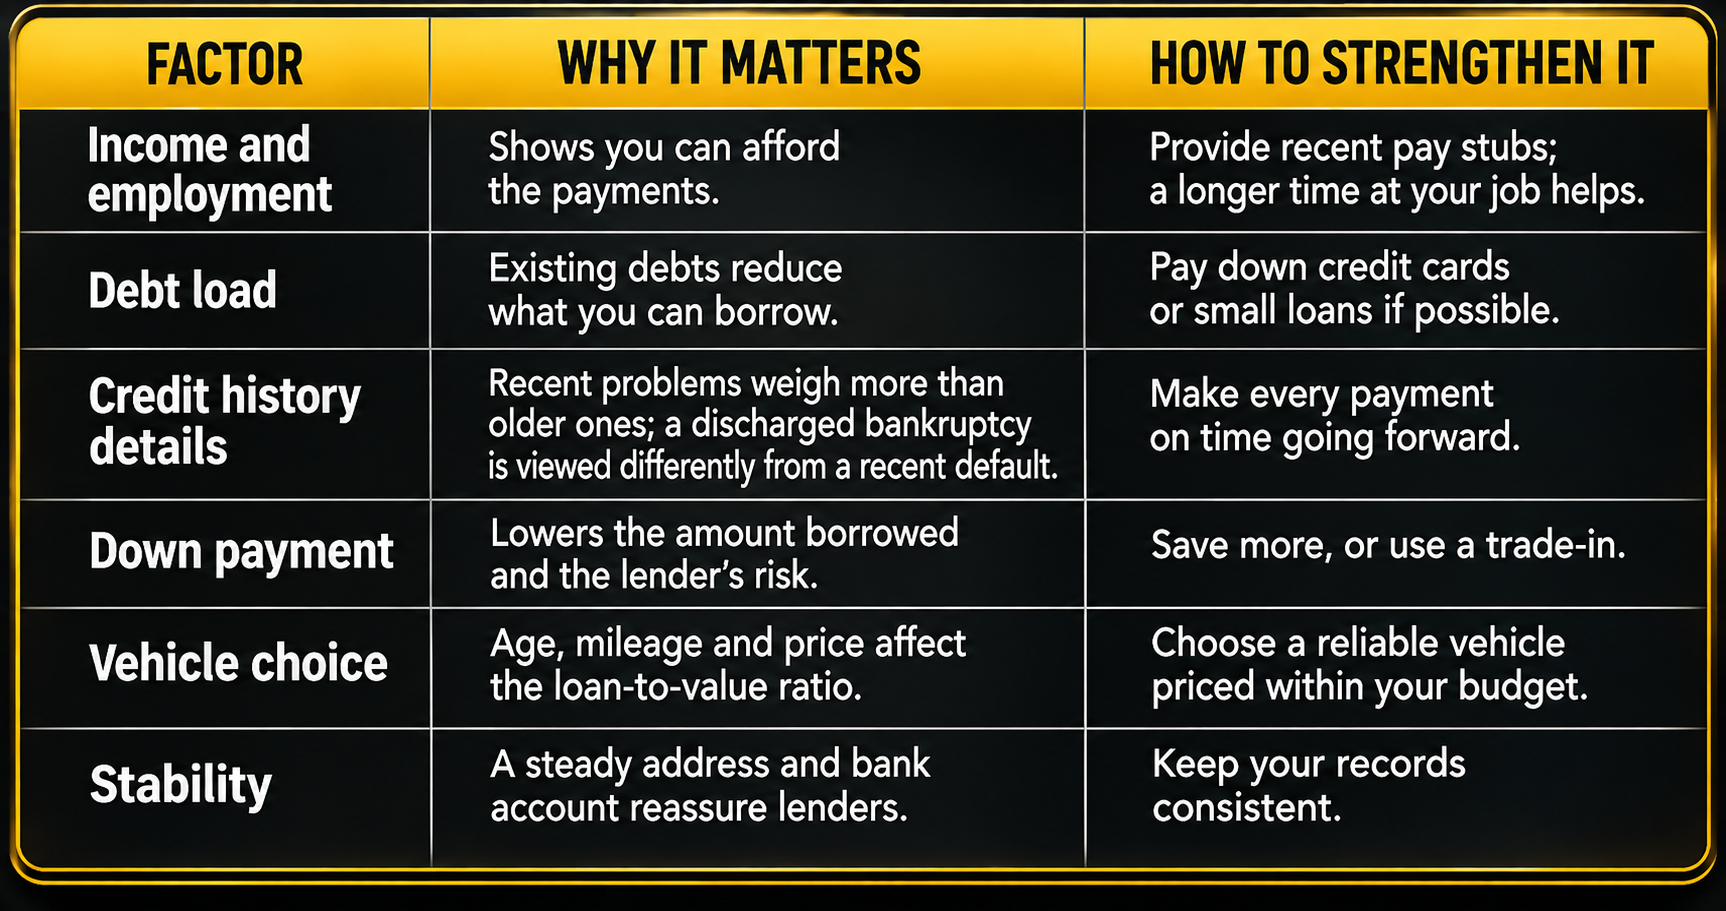
What Lenders Look At When You Apply
Bad credit lenders do not decide on your score alone. They look at the full picture:
Eligibility Requirements for Bad Credit Car Loans in Kitchener
Requirements differ by lender, but most ask for:
- Age of majority in Ontario (18 or older)
- A valid driver's licence
- Verifiable, regular income
- A Canadian address
- An active chequing account for payments
- Proof of insurance before you take the vehicle home
Some subprime lenders also set a minimum monthly income, so it is worth asking what applies to your situation.
Documents You Will Typically Need
Preparing these in advance can shorten the approval process:
- Government-issued photo ID, such as a driver's licence
- Recent pay stubs, or a job letter showing your income
- Proof of address, such as a utility bill or lease
- Void cheque or pre-authorized debit information
- Proof of insurance (often needed before delivery)
- Personal references, if the lender requests them
Newcomers to Canada may also be asked for a permanent resident card or work permit, an employment letter and Canadian bank statements.
Self-employed applicants often provide recent bank statements, a Notice of Assessment, or invoices to show steady income.
Students may be asked for proof of enrolment, income from part-time work, or a co-signer.
Interest Rates on Bad Credit Car Loans
Interest rates are the biggest cost difference between good and bad credit. For context, recent figures based on Statistics Canada data put the average new car loan rate at roughly 6.5% to 7%. Borrowers with strong credit often qualify for rates in that range or lower. Subprime auto loans are commonly quoted between about 12.9% and 29.99%, depending on the lender, the borrower's profile and the vehicle.
There is also a legal ceiling. Since January 1, 2025, the Criminal Code of Canada sets the maximum interest rate on loans, including auto loans, at 35% APR. A rate above that is a red flag.
At B Town Autos Tricity, our advertised financing starts from 6.29% O.A.C. That is a starting rate for approved credit. Your actual rate depends on your credit profile, the lender, the vehicle and the term.
What a Higher Rate Really Costs
Here is a simple example on a $20,000 loan over 60 months (illustrative only, not an offer):
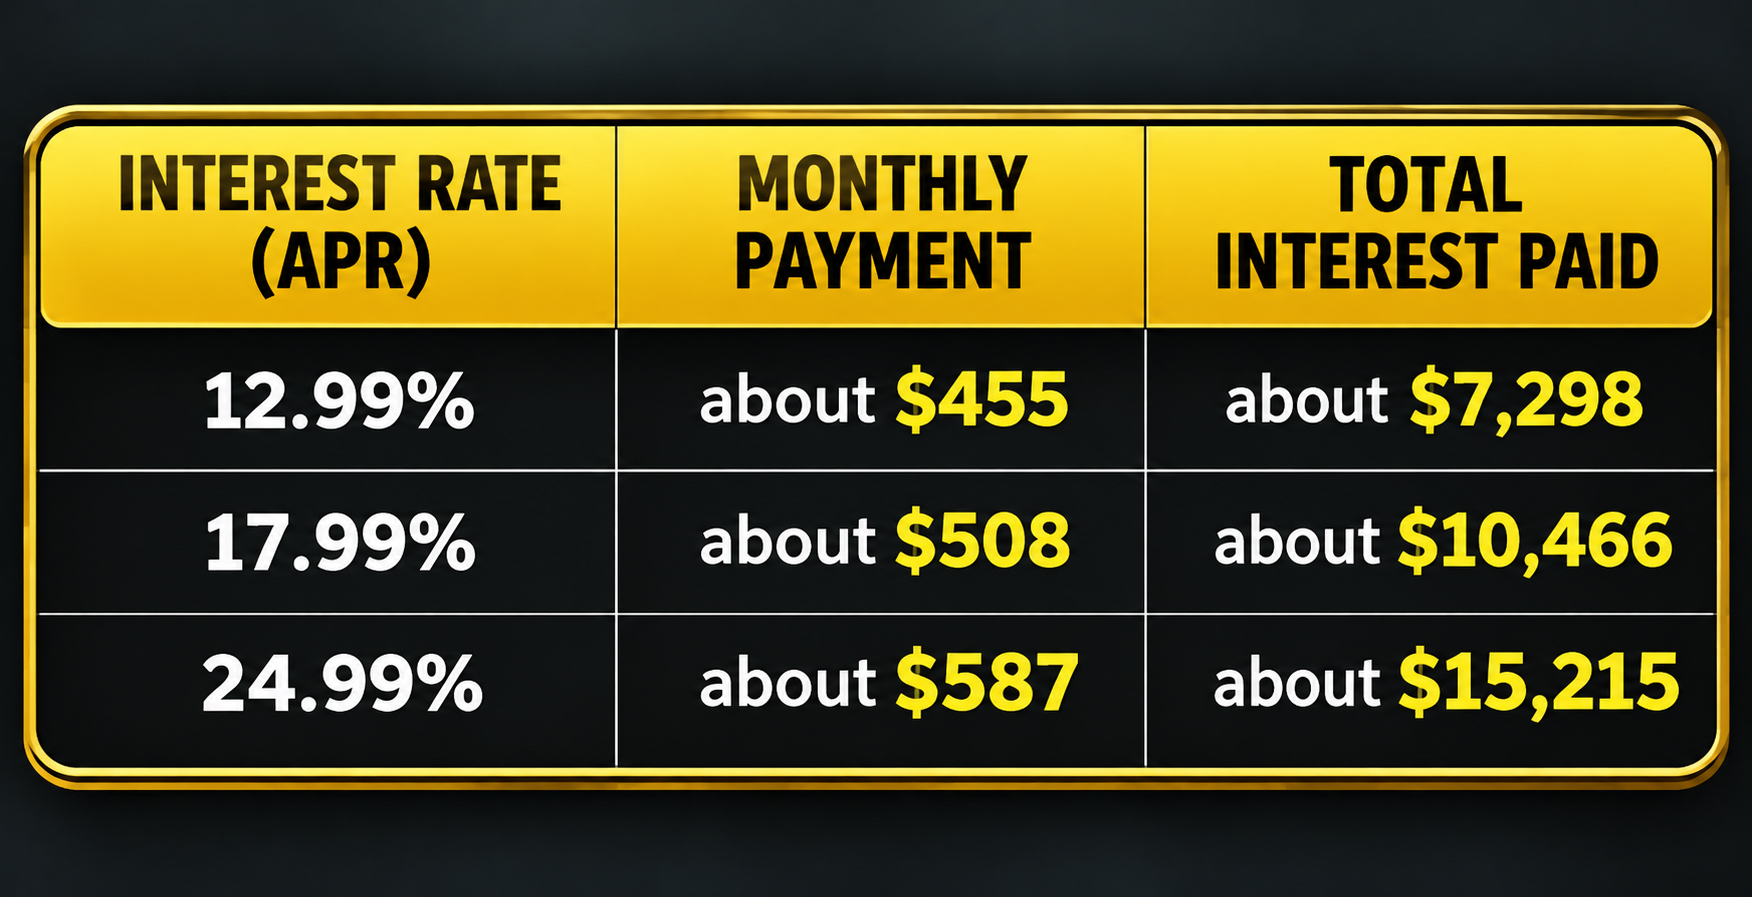
The same vehicle can cost thousands more depending on the rate, which is why comparing offers matters.
Loan Terms: How Long Should You Borrow For?
Car loan terms commonly run from 36 to 84 months, and some lenders offer longer. A longer term lowers the monthly payment but increases the total interest. Using the same $20,000 loan at 17.99%:
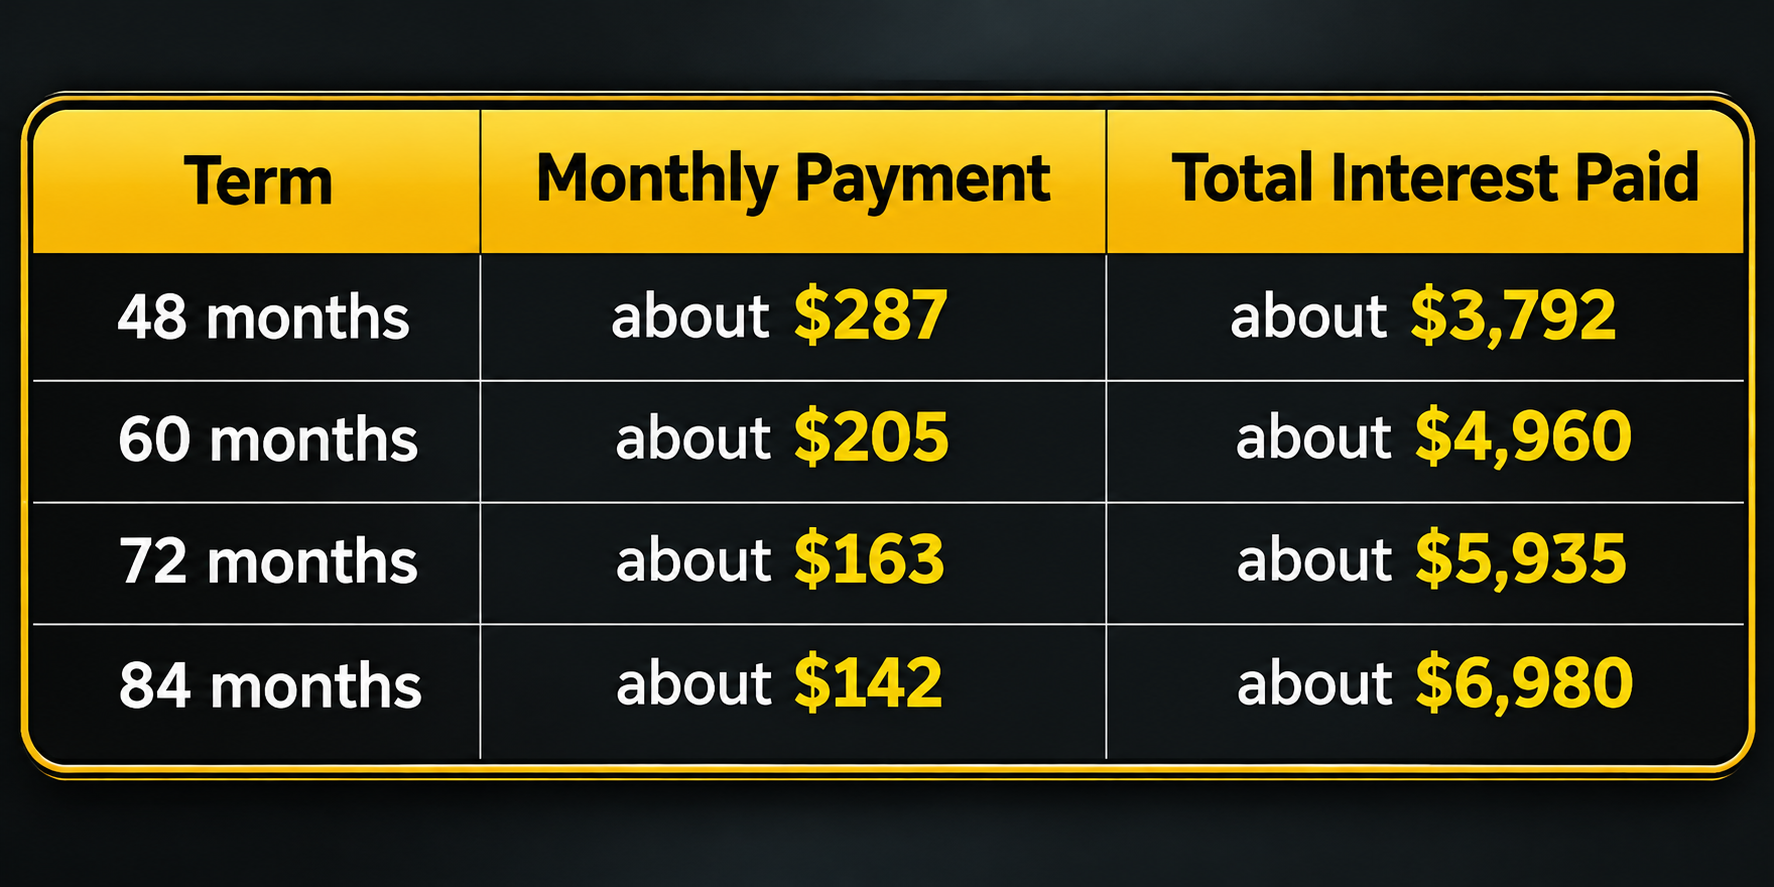
A practical approach is to choose the shortest term you can pay comfortably. Long terms on older vehicles can leave you owing more than the vehicle is worth. Ask whether you can make extra payments or pay the loan off early without a penalty.
Truck Loans with Bad Credit: What Is Different?
A truck loan works much like a car loan, but a few details change the picture:
- Higher prices mean larger loans. Trucks often cost more than sedans, so lenders look closely at your income and the loan amount compared with the truck's value.
- Used trucks tend to hold their value. That can work in your favour, since lenders feel more secure when the vehicle keeps its value.
- Work use matters. If you will use the truck for your job, tell the lender up front. Self-employed buyers may need business bank statements, a Notice of Assessment or invoices.
- Running costs are higher. Insurance, fuel and maintenance usually cost more, so include them in your budget, not just the payment.
If your credit is limited, a larger down payment, a lower-priced truck or a co-signer can improve your chances. You can browse our current used inventory to see which trucks and SUVs are available right now.
Bad Credit Car and Truck Loans for Kitchener, Waterloo and Cambridge Drivers
Getting around Waterloo Region often means a vehicle is a necessity, not a luxury, for commuting, getting to class or covering winter roads.
Kitchener
Our dealership is on Victoria Street North in Kitchener, so local buyers can visit in person, review their options and ask questions face to face.
Waterloo
Waterloo drivers include students, young professionals and families, all of whom may face limited or newly built credit. A reliable, affordable used vehicle is often the most practical starting point. Our guide to the best used cars under $10,000 in Kitchener is a useful place to start.
Cambridge
Drivers in Cambridge are a short drive from our Kitchener location and are welcome to apply for financing and visit us to compare vehicles. If you are shopping around Cambridge, the same advice applies: prepare your documents, set a budget and compare the full cost of each offer.
How to Improve Your Chances of Approval
You cannot change your credit history overnight, but you can strengthen your application:
- Save a larger down payment. Even a modest increase lowers the amount borrowed and the lender's risk.
- Consider a co-signer. A co-signer with stronger credit can improve both approval odds and the rate. They share responsibility for the loan, so discuss this carefully.
- Correct credit report errors. Dispute anything inaccurate with the credit bureau.
- Pay down revolving debt. Lower credit card balances can improve your score and your debt ratios.
- Choose a vehicle within your budget. A lower price means a smaller loan, which is easier to approve.
- Show stable income. Gather recent pay stubs or bank statements that show consistent deposits.
- Get an insurance quote first. This avoids surprises that could push your total cost above budget.
- Apply within a short window. Credit bureaus often group multiple auto loan inquiries made close together, so shopping around does not necessarily mean repeated score drops. Ask a lender how it handles this.
Red Flags to Watch For
Most dealerships and lenders operate fairly, but be cautious if you see:
- "Guaranteed approval" claims with no review of your application. Every lender assesses risk.
- Large upfront fees before any loan is approved.
- An interest rate above 35% APR, which exceeds Canada's legal limit.
- Pressure to sign quickly without a written breakdown of the rate, term, payment and total cost.
- An unclear price. Ask for the full price, including taxes and fees.
Buying from an OMVIC-registered dealer adds a layer of consumer protection in Ontario. You can also read our guide on why buying from a dealership can be safer than a private sale.
Can a Car Loan Help Rebuild Your Credit?
Yes, if it is managed well. An auto loan that reports to Equifax and TransUnion and is paid on time every month can help rebuild your score over time. Ask the lender whether your payments are reported to both bureaus. Setting up automatic payments helps you avoid missed due dates.
How B Town Autos Tricity Can Help
At B Town Autos Tricity in Kitchener, our financing team works with buyers across the credit spectrum, including those with bad credit, new Canadians and students. Financing starts from 6.29% O.A.C., and if a bank has previously declined you, we can still review your application with our lenders. The process is simple: apply online, our team reviews your options with our lenders, and you choose a vehicle that fits your approved budget. If you have a vehicle to trade in, you can get a trade-in estimate to put toward your down payment.
Frequently Asked Questions
Can I get a car loan with bad credit in Kitchener?
Yes. Many dealerships and lenders in Kitchener work with buyers who have bad credit. Approval depends on your income, debts, down payment and the vehicle you choose, not just your credit score. Expect a higher interest rate than a buyer with strong credit.
What credit score do I need for a car loan in Canada?
There is no single minimum. Scores of about 660 and above generally get the best rates, but it is possible to be approved with a lower score, or with no credit history, if your income and down payment are strong. Lenders that specialize in subprime credit often focus on your ability to repay.
Can I get a truck loan with bad credit?
Yes, though trucks often involve larger loan amounts, so lenders look closely at your income and the truck's value. A bigger down payment, a lower-priced truck or a co-signer can improve your chances. If you use the truck for work, share your business income documents.
How much down payment do I need for a bad credit car loan?
It varies by lender and vehicle. A larger down payment lowers the amount borrowed, can lower your payment, and often improves your chance of approval. Ask the finance team what amount works for your situation.
Will applying for a car loan hurt my credit score?
A credit application can result in an inquiry on your report, which may cause a small, temporary dip. Credit bureaus often treat several auto loan inquiries made close together as one, but ask the lender how it works before you apply.
Can I get approved if a bank already declined me?
Often, yes. Banks have stricter requirements, while dealership finance teams can work with lenders that specialize in subprime and newcomer financing. A previous decline does not automatically rule you out.
Can drivers from Waterloo and Cambridge apply for financing in Kitchener?
Yes. Drivers from Waterloo, Cambridge and the surrounding area are welcome to apply for financing and visit our Kitchener location to view vehicles.
Final Thoughts
Bad credit does not have to stop you from getting a vehicle. Understand how approval works, prepare your documents, compare the total cost of each offer and choose a loan term you can manage. Whether you need a car or a truck loan in Kitchener, Waterloo or Cambridge, a realistic budget and a well-prepared application make the biggest difference.